Business Plan Template: The Section Investors Read First Is Never the Summary
 Written by Martin J.
You wrote the file and you would still struggle to say which page a lender opens first. Four readers open it for four different reasons, and only one of them was in the room when you wrote it. Which one?
You spent the weekend on the executive summary and edited it three times, because it is the page everyone says matters most. It is also the page most readers skim, while the two sections that decide the answer get written last and proofread least. That gap opened quietly and no template will point at it, because a generic file has to serve every reader it might reach. Which means the arithmetic a lender came looking for may not be in your document at all, and nothing in your analytics will tell you it is missing. You find out when it comes back with a request for more information.
Who Is Reading It, and What Changes
Look at what actually holds the top of this result and the picture is consistent. A community bank's own template page is up there, two large brands are up there with downloadable files, two raw PDFs sit in the organic run, a pair of Pinterest boards have moved in, and the editorial guides come from monday.com, shopify.com and liveplan.com. Several pages in the top ten hand you a template, and more than one of them is written by a lender.
What none of them does is map the reader to what changes in the document. A downloadable file has to stay generic, which is exactly why it cannot make that call for you. Four people can read your plan, and they open it with four different questions.
The Investor Reads for the Market
Seed deck research from DocSend puts average investor review at 3 minutes 44 seconds, with only 58 percent of decks read to the final slide and the first page receiving more than twice the time of any page after it. Those are deck numbers rather than plan numbers, and I am not going to pretend otherwise, but they are the closest measured evidence that the front of a document decides whether the rest of it gets read. An investor's first three minutes go on one question: is this market big enough to return a fund, and can this team take a share of it? A document that spends its opening pages on a repayment schedule answers a question this reader never asked.
A business plan itself is a different instrument, and the comparison is the cleanest public framing of the difference. A plan takes twenty minutes or more and often hours, and it gets read in full only once interest already exists. So the investor's first pass is a filter, and the plan is what they open after the filter lets you through.
The Bank Reads for the Repayment
The Small Business Administration rewrote the lending floor in SOP 50 10 8.1, effective 1 October 2026. Debt service coverage minimums are 1.10x for 7(a) Small loans and 1.15x for Standard 7(a), with 1.25x and 1.15x applying by change-of-ownership type. A start-up has to show a 10 percent equity injection, and personal guarantees are required from anyone holding 20 percent or more.
Then there is the layer the regulation does not mention. Most banks apply their own overlay on top, commonly 1.25x or higher on business debt service coverage, and many also compute a global DSCR that folds in the owner's personal income and personal debt and looks for 1.0x to 1.15x on that combined figure. Lenders describe their comfort zone as 1.25 or higher, ideally closer to 2, and one capital provider puts the preferred line above 1.40.
All of which means a credit officer reads your repayment arithmetic first, not your vision. They are asking what the monthly payment looks like in your worst month, not your average one. Four payments a year at 1.4x coverage and eight months at break-even is a different application than the annual total suggests.
There are two more 2026 changes quietly invalidating older guide content. The FICO SBSS prescreen requirement for 7(a) Small loans of $350,000 or less ended on 1 March 2026, and ownership was restricted to U.S. citizens and U.S. nationals with a principal U.S. residence. Lawful permanent residents no longer qualify. If your plan was built from a template article written before March, nothing in it will have told you that.
The Internal Reader Reads for the Owner
Your own team opens the plan for a simpler reason: to find out who is doing what. A milestone without a name is a milestone nobody has picked up. And they will compare your numbers against the ones they work with every day, which is the fastest credibility test in the document. When the marketing line in the plan contradicts the marketing budget in the finance folder, the team notices before any outside reader does.
If a chunk of that work is bought in, the operating plan has to name the outside team rather than absorb it into a total, because coordination is a real cost and it lands on whoever already has the least time. What those arrangements actually cost, and what they return, is covered in our piece on content creation agencies.
The Partner Reads for the Split
A partner or co-founder is reading for the terms that never make it into a template: what a contribution buys, what happens to the share if someone leaves in year two, and what the split looks like after a bad year rather than a good one. Those terms belong in the plan document, not in a conversation that everyone remembers differently.
Here is the same information as a single mapping, which is the piece no template in this result carries:

Reader | What they check first | What changes in the document |
|---|---|---|
Investor | Whether the market can return a fund | Market section and use of funds carry the weight; the repayment schedule is background |
Bank or credit officer | Whether the repayment arithmetic survives a bad month | Show coverage against the worst month, the equity injection and the guarantee requirement |
Internal reader or team | Whether a name sits beside every piece of work | Milestones get owners and dates; the plan has to agree with the budget |
Partner or co-founder | Whether the split holds under pressure | Contribution, vesting and exit terms are stated in the document |
The Sections That Do Work
A section is doing work when a reader can check it and the check can change a decision. By that test, most of the standard list is neutral, and two sections are decisive.
The Market Section, Written With a Number Someone Can Check
Every guide tells you to include a market analysis. Not one tells you what number belongs in it, and "the market is growing" cannot be checked by anybody. Put three numbers in the section and source each one with a date: the buyers you can actually reach, what they pay, and the share you have to win. Then write the arithmetic out, so reachable buyers times price times share equals the revenue in your own projection. A reader who can follow that chain can also disagree with a single link in it, which is what you want, because a challenge is cheaper than silence.
That same section is where the competitive half belongs, and it is a real demand pocket underneath this query. Name the seat you are taking and whose customer you are taking it from, using the same structure as our competitor analysis framework so the comparison survives being read by someone who knows the market better than you do.
One boundary worth keeping clean: if the market argument grows into a channel plan, that is a different document. A content strategy template belongs in the marketing folder, not in the funding plan. Lenders do not read channel plans and investors file them as an appendix.
The Unit Economics, Written Before the Projections
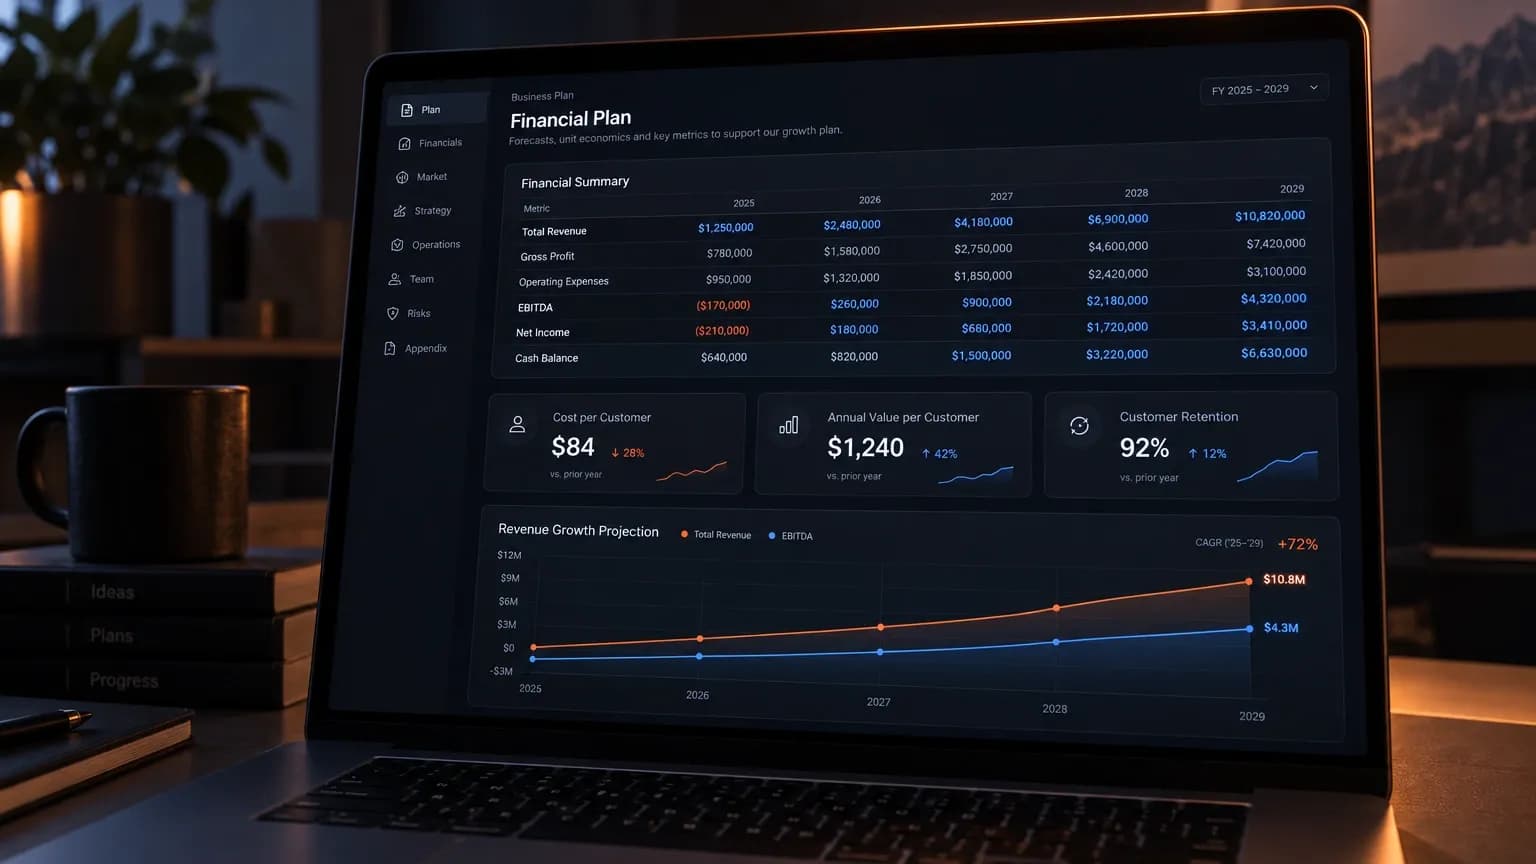
Almost every guide treats financials as one block, which is why so many plans contain a growth curve with no arithmetic underneath it. Split the job in two. Unit economics first: what it costs to acquire one customer, what that customer pays you in a year, what they cost to serve, and how long they stay. Projections second, and built from the first. Then a three-year revenue figure stops being a claim and becomes the first number multiplied by the second.
Written in the other order, the projection is a shape you liked, and the rest of the writing becomes a search for a story that supports it. Readers can tell the difference, even when they cannot say why.
The Sections That Are Ritual
Some sections exist to be filled rather than read, and in a small business their absence is cheaper than their presence. A cover sheet. A table of contents for a fifteen-page document. An organisational chart for five people. An exit strategy in an application for a bank loan, where the lender's own recovery route is the collateral, not your acquisition plan. A mission statement paragraph that says what you would like to be.
The community bank page sitting in the top of this result is the clearest example of what happens when inventory substitutes for priority: it names ten components including a cover sheet and a table of contents, which most guides drop, and it never says what the bank itself reads first. It knows its reader better than anyone else in the result and still lists components with equal weight.
This is the one honest thing a downloadable template structurally cannot do. A generic file has to serve every reader it might reach, so it cannot tell half of them to delete a chapter. Whatever you leave out, the reader's checklist does not punish you for it. Length does the opposite.
The Order to Write It In
Order is usually dispatched in a single sentence, if it appears at all, and it deserves more than that. The summary is a compression of decisions you have already made. Write it first and you are compressing decisions that do not exist yet, which is why the first draft of an executive summary tends to be a description of the business rather than a verdict about it.
The sequence that holds up:
- Unit economics. Cost to acquire a customer, annual value, cost to serve, retention.
- The market section. The three numbers, each with a source and a date.
- The operating plan. What the business does every week, who owns each piece, which milestones carry dates.
- The projections. Built from steps one and three, so every figure traces back to an input a reader can point at.
- The financing request. How much, what it buys, and what repayment looks like in your worst month.
- The risks. The three things most likely to break, and the move you make when each one does.
- The summary and executive summary. Last, from the finished sections, which is when there is something real to compress.
Step four is where most plans quietly break, because a projection standing on a growth rate traces back to nothing a reader can check. The same discipline is what turns marketing KPIs into something a team uses instead of something a slide shows.

Why the Summary Is Written Last, and Why That Is Not a Cliche
I will not dress this one up as a discovery. The two biggest editorial guides in this result already say to write the summary last, one of them as a parenthetical inside a section, the other as the first step of a process. It is table stakes, and presenting it as the insight would be dishonest.
What is missing is the rest of the order, and the reason order matters at all. A practitioner analysis puts investors at 2 to 4 minutes on the executive summary at first contact, which means the summary's only job is to make the decisive numbers visible in the first screen. Two numbers, not a summary of everything. Which two, depends entirely on which of the four readers you are writing for.
One piece of the document is not covered above. The marketing section of a plan, and the loop that keeps a plan current once it has been signed, both belong to our marketing plan template. Read that one as the revision instrument and this one as the document it revises.
Template vs Plan vs Canvas
Three words get used for one thing, and they are not the same object.
A template is a shell: headings, blank cells, and no opinion about your business. A plan is that shell filled with your numbers, your names and your dates. A canvas is a one-page map of a business model, which is genuinely useful for arguing a model in twenty minutes and structurally unable to carry a loan repayment schedule, a coverage ratio, a cost of goods line or a dated milestone. The canvas does its own job, and its own job is not this one.
The mistake is treating the shell as the deliverable. A plan that has been downloaded, renamed and half-filled scores worse with a credit officer than four pages of handwritten arithmetic, because the four pages answer the question that was asked.
Conclusion
Write the unit economics first, check the market number against a source somebody else can open, and put the summary at the end where it has something to summarize. Then hand the document to the person you are actually addressing and watch which page they turn to. That page is telling you what the plan is for, and it is rarely the one you rewrote three times on a Sunday.
There is no business plan template to download here, and that is deliberate. What sits underneath a plan like this is the data the numbers came from, and Allable reads it in one place: your search performance, your campaign spend and your content inventory side by side, so the market and marketing figures in the document can be traced back to what they actually earned. Plans start at EUR 99 a month on Pro, EUR 199 on Business and EUR 399 on Scale, and each one starts with a 7-day trial, so you can put your own figures through it before you commit a quarter to them.
FAQ
What should a business plan template include?
The standard list is settled and you can take it as given: executive summary, company description, market analysis, product or service, marketing and sales, operations, management, financial projections and the funding request. Both Google surfaces publish that list at length and neither is wrong. What decides the outcome is three things the list cannot carry: unit economics sitting underneath the projections, a market section holding a number somebody else can check, and a set of sections chosen to fit the reader you actually have. A small business serving lenders can drop the mission statement and the organisational chart without losing anything a credit officer was looking for.
How long should a business plan be?
There is no standard length, and the two answers Google publishes for this exact question do not agree. Its AI Overview says 15 to 25 pages, while its AI Mode panel, answering the same query, says 30 to 50 pages for a traditional plan. Two surfaces, one company, a factor of two apart. The SBA does not set a length either. The most useful published position comes from liveplan.com, whose own guide says a plan should not take longer than 15 minutes to skim and that length should mirror its audience. That is the right test. A lender's plan is short and forward on the arithmetic. An investor's plan can run longer if the market argument needs the room. An internal or partner plan is often one page.
Do you need a business plan to raise money?
Not always, and the answer splits by reader. Equity investors usually start from a deck, so the plan is often requested after interest already exists; the DocSend figures above show how little of the front end of a process is spent reading anything. SBA-backed debt is a different matter, because a lender is working against a named rulebook. Since 1 October 2026 that rulebook means a debt service coverage floor of 1.10x or 1.15x depending on the loan, a 10 percent equity injection for a start-up, and personal guarantees from owners above 20 percent. Only 42 percent of small business applicants received all the financing they sought in the Federal Reserve's 2026 survey reporting, so the document is doing real work rather than satisfying a formality. Write for the reader who has a ratio to check.
Read the plan against the numbers it claims
A financial section is only as good as the figures underneath it. Allable connects your search performance, your campaign spend and your content inventory in one workspace, so the market size and the customer acquisition cost in your plan can be checked against numbers that exist rather than numbers that were estimated once and copied forward.